There is a certain comfort in doing what has always worked. Established processes, familiar branch models, and proven growth strategies offer a sense of stability. But comfort can become expensive, particularly when the people an institution hopes to serve tomorrow are developing expectations that look increasingly different from those of today. As banks and credit unions prepare their 2027 strategic plans, leadership teams face a question worth asking: Are they building an institution that will attract the next generation of customers and members, or simply extending the life of yesterday’s business model? Are we actually preparing for what’s next?
The financial services industry has never lacked conversations about change. Technology, consumer behavior, competition, and operational efficiency have occupied boardroom discussions for years. Yet discussing change and preparing for it are two different exercises. Preparing for what’s next requires leadership to examine the assumptions behind current decisions, question the value of established practices, and recognize that standing still carries its own financial consequences. A strategy that protects today’s performance without considering tomorrow’s relevance may deliver a comfortable budget meeting, but it offers little assurance of future growth.
The Next Generation Is Already Changing the Conversation
Consumer expectations rarely change according to an institution’s strategic planning calendar. They develop through everyday experiences, often outside financial services. People have grown accustomed to convenience, accessibility, and experiences that recognize their individual needs. They expect their financial institution to deliver that same level of consideration, particularly when making decisions that affect their financial well-being.

Research reinforces the need to pay attention. A September 2026 study from Temenos and Celent found that 75% of surveyed U.S. banking consumers described themselves as moderately satisfied or less with their primary financial institution. The research also reported that 62% of U.S. banks found winning and retaining customers more difficult over the preceding 12 months. Satisfaction, it seems, should never be confused with loyalty.
For executives, this raises an important distinction. The next generation of customers and members may appreciate convenient transactions, but convenience alone does little to establish a meaningful financial relationship. Institutions must consider how they will deliver relevant advice, financial education, accessibility, and personal attention as consumer needs change. The opportunity is to understand what people will value next, rather than waiting for declining engagement to provide the answer.
The Branch Is Changing. Is the Strategy?
Predictions about the disappearance of physical banking have circulated for years. Yet the more productive conversation is no longer whether branches have a future. It is whether today’s branch networks are positioned to serve that future.
A September 29, 2026, PYMNTS report offers an interesting perspective. While only 28% of Gen Z consumers prefer receiving financial advice in person, 76% say they would act on personalized guidance received during an in-branch conversation. The same report found that 76% of credit union executives planning to repurpose existing branches intend to move toward advisory-focused locations.
These findings challenge the assumption that digital preference eliminates the value of physical interaction. They also suggest that maintaining a traditional branch network without reconsidering its purpose may overlook opportunities for growth.
As institutions evaluate their physical presence for 2027 and beyond, every location deserves a fresh examination. Does its placement align with current and projected market demand? Does its size support the services people actually use? Could a smaller format, retail placement, relocation, or remodel create greater value? Are employees equipped to turn a branch visit into a meaningful financial conversation?
The objective should not be to preserve every existing location or pursue expansion simply to increase branch count. It should be to develop a network in which each location has a defined purpose, supports measurable business goals, and earns its place in the institution’s long-term strategy.
A branch can have an excellent history and still be poorly positioned for the future. Sentiment is understandable. It is considerably less useful as a capital allocation strategy.
Leadership Must Prepare People for What’s Next
Physical environments and consumer expectations represent only part of the equation. An institution’s ability to evolve ultimately depends on the people responsible for delivering its strategy.
Preparing for 2027 requires executives to consider whether their teams possess the knowledge, confidence, and decision-making skills needed to support changing service models.
Technology will continue to influence how financial services operate. Automation, digital platforms, and improved access to information can create efficiencies, but their value depends on how effectively they support the customer or member experience. A faster transaction is useful. An employee who can help someone make a confident financial decision creates a different kind of value.
This distinction places greater responsibility on leadership.
Preparing for 2027 requires executives to consider whether their teams possess the knowledge, confidence, and decision-making skills needed to support changing service models. It also requires examining how employee development aligns with investments in facilities, technology, and growth.
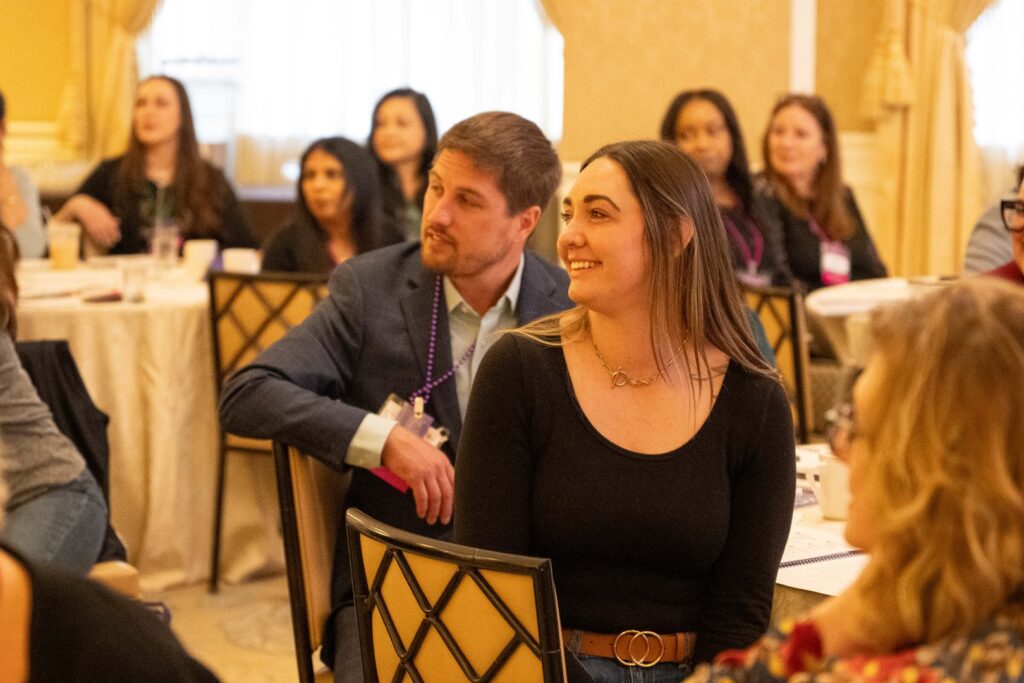
A redesigned branch staffed by employees trained exclusively for transactional service presents an obvious disconnect. So does a strategic plan that calls for relationship growth without establishing what stronger relationships should look like in daily operations.
Leadership must create alignment between the institution’s vision and the experience its people deliver. That means developing managers who can coach, employees who understand the financial needs of the people they serve, and a culture willing to question established practices when better opportunities emerge.
Change becomes considerably more difficult when the strategic plan evolves but the organization responsible for executing it does not.
The Cost of Standing Still Deserves a Place in the 2027 Budget
Strategic planning typically involves examining projected growth, operational expenses, capital investments, and anticipated returns. These are essential considerations. However, the financial impact of maintaining the status quo deserves equal attention.
What is the long-term cost of operating branches in markets that no longer align with growth objectives? What opportunities are missed when expansion decisions rely more heavily on available real estate than meaningful market intelligence? How much relationship potential goes unrealized when frontline employees lack the training or time to engage customers and members beyond routine transactions?
These questions are particularly relevant as financial institutions evaluate competing demands for capital. In its September 15, 2026, Banking CFO Insights report, PwC highlighted the increasing complexity of planning for 2027, including uncertainty surrounding efficiency targets, technology returns, and funding conditions.
For executive teams, the implication is straightforward. Future readiness must become part of today’s investment decisions. Market intelligence, branch performance, operational capacity, and consumer expectations should inform where institutions invest, what they redesign, and which practices they reconsider.
Maintaining an existing strategy may appear to be the conservative choice. Yet preserving an underperforming model simply because it is familiar can carry costs that extend well beyond the next budget cycle.
Preparing for What’s Next Starts Now
The institutions that serve tomorrow’s consumers will need to make decisions today about the experiences, relationships, and physical networks they intend to deliver. Some will expand. Others will relocate, remodel, or rethink established service models. All will need leadership capable of recognizing when familiar approaches no longer support future objectives.
Preparing for what’s next does not require predicting every industry development between now and 2030. It requires the willingness to question whether current investments, employee capabilities, and growth strategies reflect the needs of the people an institution hopes to serve.
As 2027 approaches, perhaps the most valuable question leadership teams can bring to their strategic planning discussions is also the simplest:
If the institution were being built today to serve the customer or member of 2030, would it look, operate, and deliver the same experience it does now?
The answer deserves more than a passing conversation. It deserves a place in the strategic plan.
Leave a Reply